1 March, 2021
Sue Trinh, Senior Macro Strategist
Global stock markets corrected last week (as of 26 February) as the 10-year US Treasury yield climbed to its highest level since February 20201. The rise unnerved investors who fear that higher inflation will spur an-earlier-than-indicated rate hike from the US Federal Reserve (the Fed). In this note, we share our thoughts on rising bond yields, global liquidity, and the implication for equities.
Market focus has concentrated on rising bond yields and fears that higher inflation will spur the Fed to raise interest rates. However, as our Chief Economist Frances Donald mentioned in her earlier note, we believe that markets have been overemphasising the inflation aspect of the Fed's mandate. This is why we are skeptical that the US central bank will taper its quantitative-easing measures any time soon. Indeed, in our view, the employment side of the mandate will restrain the tapering conversation until at least the third quarter.
It’s also worth noting that although the Fed has signaled it’s unlikely to add any additional easing aimed at the real economy, the Bank of England, the European Central Bank, and the Bank of Canada have all made it clear that rate cuts remain on the table. While we don’t expect these central banks to cut rates, we believe that relative monetary policy divergences between the Fed and other major central banks are only going to get wider. The one exception here being the People’s Bank of China, which is in tightening mode.
That said, we have been closely watching the slowdown in global liquidity growth. In level terms, global liquidity (proxied by global money supply) has topped out in 2021, flat-lining around US$96 trillion year-to-date . Importantly, the growth in global liquidity has slowed markedly, from 40%+ to 4.8% on a three-month percentage-change basis, with slowing balance-sheet expansion from the Fed and the People’s Bank of China (PBOC), as the major drivers of this dynamic.
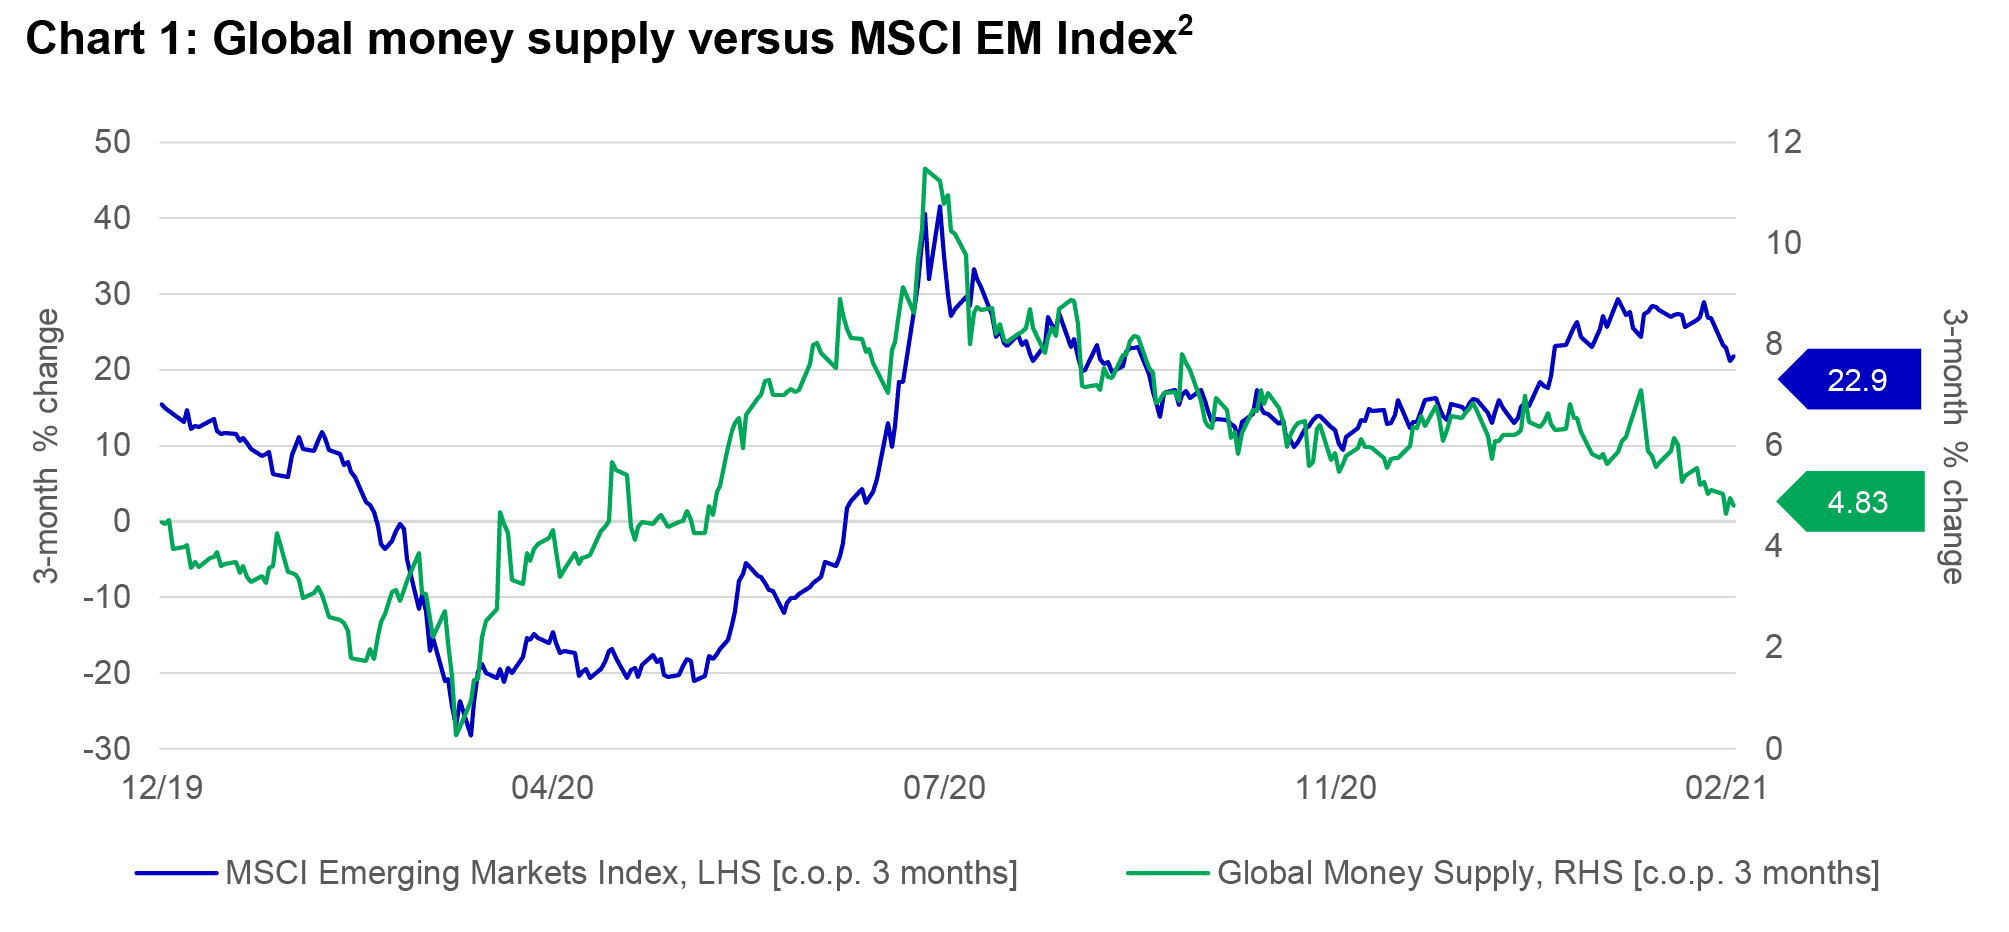
Chart 1 shows the three-month growth in global liquidity (green line) against the three-month change in MSCI EM equities. In our view, the chart has been flashing a warning sign in that EM equities had become overextended relative to global liquidity growth.
This is corroborated by Chart 2, where we adjust and normalise the market capitalisation of developed markets (DM) and EM equities for global liquidity. By this metric, the market cap of EM is running over 1 standard deviation above its long-term average. In contrast, the market cap of DM is not stretched.
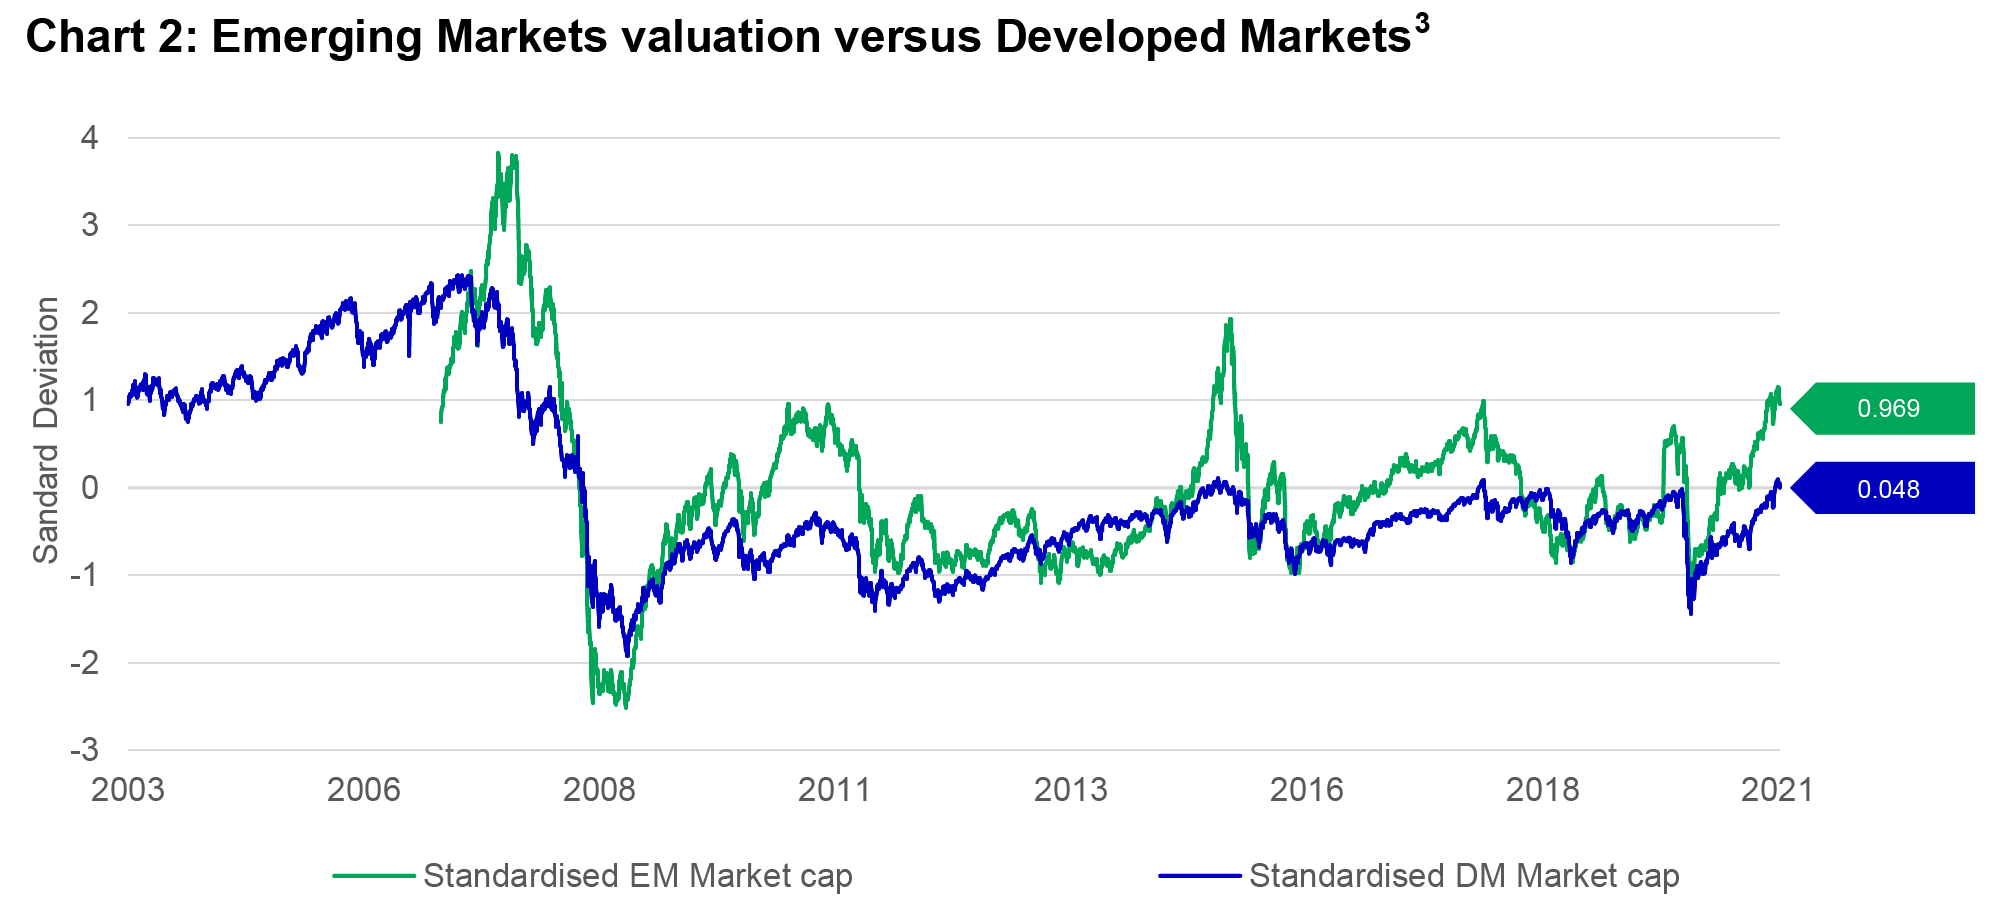
Taken together, this suggests that after the recent strong price recovery, EM may be stretched vis-à-vis DM. At the very least, it implies near-term consolidation. Longer-term, we remain bullish on EM equities, particularly in Asia, and would view any correction as an opportunity. Meanwhile, on a global basis, the largest central banks have likely hit peak liquidity. In our view, the respective biases of the various major central banks strengthen our belief that the US dollar could experience some countertrend rallies in the short term, which tend to be supportive of US equities.
Fed hikes rates for first time since 2023 as expected
Today’s Federal Open Market Committee (FOMC) decision and press conference went smoothly—a welcome development, in our judgment, after the mixed signals that emerged from the Fed’s July meeting. The rate decision: A 25 basis-point (bps) hike, bringing the federal funds rate from 3.75% to 4.00%.
Beyond AI hype: How Manulife Global Multi Asset Diversified Income Fund (GMADI) evaluates long-term equity opportunities
AI continues to create potential investment opportunities, but we believe not every AI-related company will become a long-term winner. Rather than maximising exposure to the theme, the Manulife Global Fund - Global Multi-Asset Diversified Income Fund takes a selective and valuation-aware approach. In this investment note, we discuss the three characteristics we look for when identifying long-term winners and how these principles are reflected in the Fund's equity sleeve which currently maintains a constructive view on sectors such as communication services, healthcare, consumer staples and energy. This positioning reflects our bottom-up conviction in individual businesses whose long-term fundamentals, cash flow characteristics and valuations are viewed favourably by the investment team.
Asia High Yield has reached new highs; what’s next?
Asia High Yield (HY) bonds, known for providing an attractive source of income, present a very different opportunity set today compared to the pre-pandemic era. As discussed in our investment note from nearly a year ago, the asset class is no longer dominated by Chinese Mainland property developers. Instead, it has become more diversified, with investment opportunities spanning multiple areas, such as financial institutions, gaming operators, infrastructure providers, and selected frontier markets.
1 Bloomberg, as of 26 February 2021.
2 Bloomberg, Macrobond, Manulife Investment Management, as of 25 February 2021.
3 Bloomberg, Macrobond, Manulife Investment Management, as of 26 February 2021.
Fed hikes rates for first time since 2023 as expected
Today’s Federal Open Market Committee (FOMC) decision and press conference went smoothly—a welcome development, in our judgment, after the mixed signals that emerged from the Fed’s July meeting. The rate decision: A 25 basis-point (bps) hike, bringing the federal funds rate from 3.75% to 4.00%.
Beyond AI hype: How Manulife Global Multi Asset Diversified Income Fund (GMADI) evaluates long-term equity opportunities
AI continues to create potential investment opportunities, but we believe not every AI-related company will become a long-term winner. Rather than maximising exposure to the theme, the Manulife Global Fund - Global Multi-Asset Diversified Income Fund takes a selective and valuation-aware approach. In this investment note, we discuss the three characteristics we look for when identifying long-term winners and how these principles are reflected in the Fund's equity sleeve which currently maintains a constructive view on sectors such as communication services, healthcare, consumer staples and energy. This positioning reflects our bottom-up conviction in individual businesses whose long-term fundamentals, cash flow characteristics and valuations are viewed favourably by the investment team.
Asia High Yield has reached new highs; what’s next?
Asia High Yield (HY) bonds, known for providing an attractive source of income, present a very different opportunity set today compared to the pre-pandemic era. As discussed in our investment note from nearly a year ago, the asset class is no longer dominated by Chinese Mainland property developers. Instead, it has become more diversified, with investment opportunities spanning multiple areas, such as financial institutions, gaming operators, infrastructure providers, and selected frontier markets.
©1999 - 2026 Manulife Investment Management (Hong Kong) Limited