10 November 2026
June Chua, Head of Asia Equities
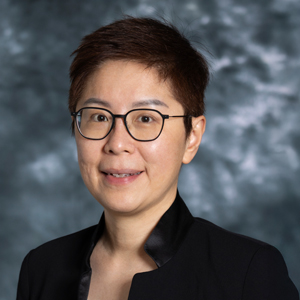
June Chua, Head of Asia Equities, shares her latest perspectives on what the US mid-term election results could mean for Asian equities. While selected markets and sectors may see near-term volatility as investors assess the implications for fiscal policy, trade, regulation and US Treasury yields, the overall impact on Asian equities may be limited. More importantly, domestic growth drivers, policy priorities and company fundamentals are likely to remain the key drivers of the region’s equity markets.
China and Hong Kong equity markets registered positive gains during the week of 2 November 2026, with the MSCI China Index gaining 5.3% and the Hang Seng Index rising 5.1%, while the Shanghai Composite Index rose 1.4%1.
While trade-related uncertainties between the Chinese Mainland and the US may not disappear entirely, any moderation in tariff policies would be positive for the Chinese Mainland overall.
Over the past four years, the Chinese Mainland has already diversified its export destinations away from the US and increasingly towards emerging markets. Year to date in 2026, the Chinese Mainland’s exports have continued to show strong growth (36.3% year-on-year versus +25.0% year-on-year in August 2026), supported by export demand for technology and advanced manufacturing products. We also believe moderating oil prices should benefit the Chinese Mainland’s exporters and downstream sectors, including chemicals and refining.
In healthcare, as US Democrats consider policies aimed at healthcare affordability and broader access to lower-cost drugs, this may potentially benefit Chinese Mainland biotechnology companies pursuing out-licensing opportunities, while US pharmaceutical companies face patent expiries for their drugs.
In the data centre space, US data centre capacity constraints may lead to some demand spilling over into Asia, while rising computing demand in the Chinese Mainland and supportive policy dynamics should underpin data centre build-out across the Chinese Mainland and the rest of Asia. The Chinese Mainland may also benefit from the global expansion of data centre infrastructure, given that it accounts for approximately 60% of the global market for optical modules and around 60% of the global market for printed circuit boards (PCBs) and copper-clad laminates (CCLs).
More importantly, the Chinese Mainland continues to pursue greater technological self-sufficiency, which should benefit the broader domestic AI supply chain. The Chinese Mainland is reportedly developing a five-year roadmap for national AI data centres, targeting approximately RMB2 trillion for nationwide AI computing clusters and at least 80% domestic technology adoption2. As such, these initiatives should benefit the local supply chain.
In industrials, the investment team continues to see significant opportunities, given the Chinese Mainland’s sizeable market share in advanced manufacturing equipment. The sector should continue to benefit from Chinese companies’ overseas expansion, supported by the country’s relative cost advantages and competitive positioning.
Taiwan’s equity market underperformed the rest of the region during the week of 2 November 2026, declining 12.2%, dragged by the technology-related supply chain1. In terms of fund flows, qualified foreign institutional investors were net sellers of cash equities, while domestic funds were net buyers across sectors. After the market close on 6 November 2026, Taiwan’s financial regulator stepped in to cap the volume of intraday short-selling orders for borrowed securities at 3% and announced its readiness to deploy the NT$500 billion stock stabilisation fund. The Taiwan equity market subsequently rebounded 4.9% on 9 November 20261.
The investment team believes that the real surprise was not the Democratic win itself, but the breadth of the result, with the outcome in Texas pointing to a more uncertain policy backdrop for future AI data centre build-out in the US. However, the team does not see an immediate impact on committed plans for 2027-2028, although visibility beyond 2028-2029 has reduced, particularly given the potential for greater scrutiny of data centre approvals and power consumption.
Over the medium to longer term, we expect the AI investment cycle to broaden from a focus on “faster chips” to “better systems”, with networking and interconnect infrastructure, as well as power and cooling systems, becoming increasingly important bottlenecks and potential sources of growth in semiconductor and infrastructure content.
For Asia more broadly, the investment team believes that policy changes following the election may affect the pace of data centre build-out in the US. Industry models estimate US data centre additions of around 62 GW by 2028, with much of this capacity yet to enter construction. Texas, Ohio and Georgia account for roughly 25 GW of the planned capacity, contributing to market concerns over whether some of these projects could be delayed or ultimately not proceed.
However, the investment team estimates that available chip supply could support only around 35-40 GW of new US data centre capacity in 2028, well below the planned 62 GW. As a result, many of these planned data centres would likely have had to wait for sufficient chip supply in any case. Furthermore, securing an adequate power supply remains an important constraint on data centre development.
From an investment perspective, we believe the mispricing across the Asian AI supply chain may create opportunities for medium-term investors. The investment team sees the next phase of the AI growth narrative moving from conversational applications towards paid work applications and robotics, potentially broadening the range of beneficiaries across the regional technology supply chain.
Looking ahead, key developments to monitor include the results of a global US chip provider in late November, 2027 capital expenditure budgets from hyperscalers in January 2027, and the US Federal Reserve’s December 2026 meeting, particularly for signals on the direction of interest rates.
For India, we continue to favour healthcare and industrials, where we see limited medium-term impact from the US mid-term election outcome. A Democratic-controlled Congress could support higher healthcare spending, which would be positive for the sector. A stronger US focus on renewable energy could also benefit Indian renewable energy companies. Conversely, any slowdown in US capital expenditure could create near-term headwinds for Indian industrial companies with US exposure.
From a broader market perspective, lower US bond yields would ease financial conditions and be supportive of Indian equities.
Within the technology sector, we remain cautious on large-cap Indian IT services companies, where AI-driven productivity gains are creating revenue deflation. We are more selective within the mid-cap IT space, favouring companies that enable corporate AI adoption while having limited exposure to legacy businesses.
1 Bloomberg, 9 November 2026. Returns in index currencies. Past performance information presented is not indicative of future performance.
2 Source: Morgan Stanley research, November 2026
美國中期選舉:最新結果對投資者有何啟示?
多元資產方案首席投資總監及環球股票高級組合經理 Nathan W. Thooft,剖析美國中期選舉對投資市場的啟示。
康健護理業:應對政策、利率及長期需求的轉變
醫療保健業並非單一或同質化的投資類別。利率及獲取資本的情況可影響企業融資和公司活動。評估醫療保健業時,應考慮企業基本因素、估值、財務韌性、監管風險,以及企業在提高醫療服務效率的同時,應對尚未獲滿足醫療需要的能力。
美國中期選舉前宜保持觀望?歷史對市場表現與行為的啟示
隨著美國11月中期選舉臨近,媒體報道愈趨熱烈,或令部分投資者傾向暫時觀望。我們認為,回顧歷史有助了解選舉周期前後的市場表現。本文探討過去數十年的選舉周期數據可能帶來的啟示,以及為何保持耐性往往至關重要。
美國中期選舉:最新結果對投資者有何啟示?
多元資產方案首席投資總監及環球股票高級組合經理 Nathan W. Thooft,剖析美國中期選舉對投資市場的啟示。
康健護理業:應對政策、利率及長期需求的轉變
醫療保健業並非單一或同質化的投資類別。利率及獲取資本的情況可影響企業融資和公司活動。評估醫療保健業時,應考慮企業基本因素、估值、財務韌性、監管風險,以及企業在提高醫療服務效率的同時,應對尚未獲滿足醫療需要的能力。
美國中期選舉前宜保持觀望?歷史對市場表現與行為的啟示
隨著美國11月中期選舉臨近,媒體報道愈趨熱烈,或令部分投資者傾向暫時觀望。我們認為,回顧歷史有助了解選舉周期前後的市場表現。本文探討過去數十年的選舉周期數據可能帶來的啟示,以及為何保持耐性往往至關重要。