13 March, 2020
Endre Pedersen, Chief Investment Officer Fixed Income, Asia ex-Japan
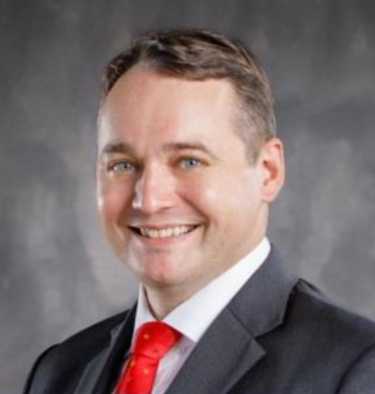
The steep decline in oil prices during the week of 9 March 2020 sent global markets sharply lower. However, Asia may emerge as a principal beneficiary of this trend, as many countries in the region are net oil importers. In this investment note, Endre Pedersen, Chief Investment Officer, Fixed Income, Asia (ex-Japan), explains why Asian fixed income may be well placed to withstand short-term market volatility and how to capture long-term opportunities for investors.
The recent sharp decline in oil prices, coupled with the ongoing risk-off market environment, introduced additional volatility and uncertainty to global and Asian financial markets.
During periods of heightened volatility, investors are unlikely to appreciate the contrast between the region’s “winners” and “losers” that come from lower oil prices. For example, on 9 March, the Korean won, and Indian rupee both weakened against the US dollar, despite South Korea and India being beneficiaries of oil-price weakness.
Similarly, Asian credits lack differentiation at this juncture, as most Asian credit spreads widened given the already thin market liquidity conditions. We believe that some of these dislocations are driven more by market sentiment than fundamentals.
In our view, the following markets will benefit or be hurt by lower oil prices.
Once markets stabilise, the sharp fall in US Treasury yields and increased Asian yield premiums (versus developed-market bonds) should be broadly supportive for Asian hard- and localcurrency bonds. Notably, the currencies of Asia’s net energy importers should outperform on a relative basis. In the medium term, with US Treasury yields lower and the spread of COVID-19 largely contained in Asia, liquidity conditions should normalise, and this will help to recover some of these price dislocations.
Furthermore, we think that high-quality Asian investment-grade (IG) credits, including most government-backed oil names, will continue to see strong support. However, gaming and commodity issuers in the private sector may face headwinds. Investors should be more selective in credit screening for these sectors.
Fed hikes rates for first time since 2023 as expected
Today’s Federal Open Market Committee (FOMC) decision and press conference went smoothly—a welcome development, in our judgment, after the mixed signals that emerged from the Fed’s July meeting. The rate decision: A 25 basis-point (bps) hike, bringing the federal funds rate from 3.75% to 4.00%.
Asia High Yield has reached new highs; what’s next?
Asia High Yield (HY) bonds, known for providing an attractive source of income, present a very different opportunity set today compared to the pre-pandemic era. As discussed in our investment note from nearly a year ago, the asset class is no longer dominated by Chinese Mainland property developers. Instead, it has become more diversified, with investment opportunities spanning multiple areas, such as financial institutions, gaming operators, infrastructure providers, and selected frontier markets.
Global Multi Asset Diversified Income Strategy (GMADI) update: A balanced approach to market volatility
Global equity markets have recently experienced sharper movements, particularly in areas linked to artificial intelligence (AI). Earnings announcements from AI hardware, semiconductor and large cloud-computing companies have been key sources of volatility. Concerns about potential interest rate hikes have added to uncertainty. The Global Multi Asset Diversified Income (GMADI) Strategy has not been immune to these market movements. However, its income focus, broad diversification and relatively defensive positioning may help limit the effect of sharp changes in technology and growth-related investments.
Fed hikes rates for first time since 2023 as expected
Today’s Federal Open Market Committee (FOMC) decision and press conference went smoothly—a welcome development, in our judgment, after the mixed signals that emerged from the Fed’s July meeting. The rate decision: A 25 basis-point (bps) hike, bringing the federal funds rate from 3.75% to 4.00%.
Asia High Yield has reached new highs; what’s next?
Asia High Yield (HY) bonds, known for providing an attractive source of income, present a very different opportunity set today compared to the pre-pandemic era. As discussed in our investment note from nearly a year ago, the asset class is no longer dominated by Chinese Mainland property developers. Instead, it has become more diversified, with investment opportunities spanning multiple areas, such as financial institutions, gaming operators, infrastructure providers, and selected frontier markets.
Global Multi Asset Diversified Income Strategy (GMADI) update: A balanced approach to market volatility
Global equity markets have recently experienced sharper movements, particularly in areas linked to artificial intelligence (AI). Earnings announcements from AI hardware, semiconductor and large cloud-computing companies have been key sources of volatility. Concerns about potential interest rate hikes have added to uncertainty. The Global Multi Asset Diversified Income (GMADI) Strategy has not been immune to these market movements. However, its income focus, broad diversification and relatively defensive positioning may help limit the effect of sharp changes in technology and growth-related investments.
©1999 - 2026 Manulife Investment Management (Hong Kong) Limited